
四环医药:医美领军与创新药先锋,被低估的转型样本

重塑认知:四环医药(0460.HK)的深度价值重估之路 ——医美领军与创新药先锋,被低估的转型样本
Core Investment Thesis
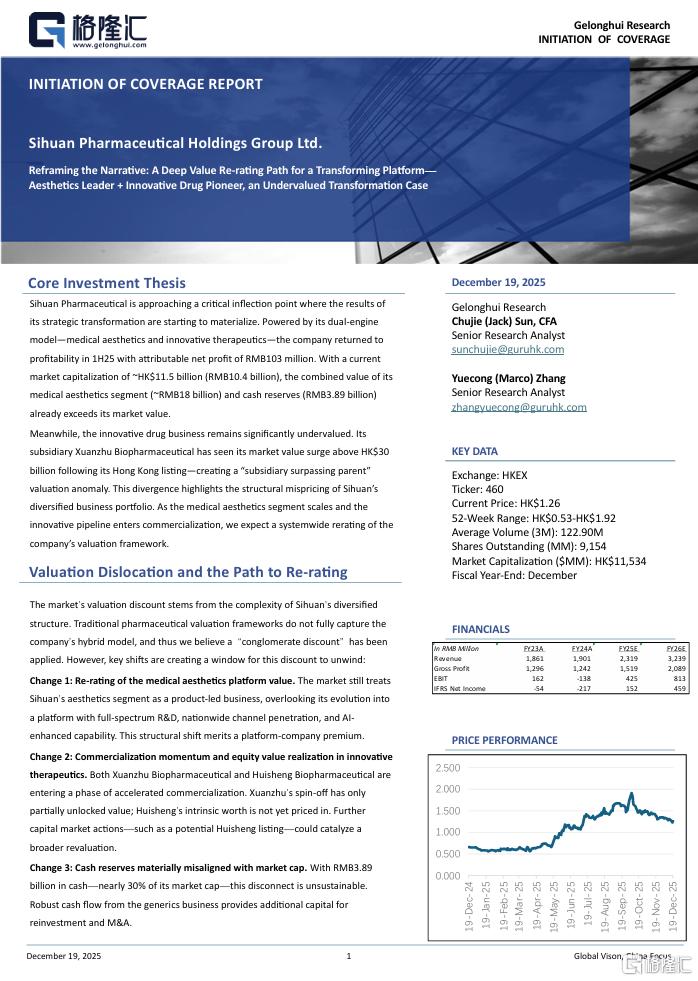
Sihuan Pharmaceutical is approaching a critical inflection point where the results of its strategic transformation are starting to materialize. Powered by its dual-engine model—medical aesthetics and innovative therapeutics—the company returned to profitability in 1H25 with attributable net profit of RMB103 million. With a current market capitalization of ~HK$11.5 billion (RMB10.4 billion), the combined value of its medical aesthetics segment (~RMB18 billion) and cash reserves (RMB3.89 billion) already exceeds its market value.
Meanwhile, the innovative drug business remains significantly undervalued. Its subsidiary Xuanzhu Biopharmaceutical has seen its market value surge above HK$30 billion following its Hong Kong listing—creating a “subsidiary surpassing parent” valuation anomaly. This divergence highlights the structural mispricing of Sihuan’s diversified business portfolio. As the medical aesthetics segment scales and the innovative pipeline enters commercialization, we expect a systemwide rerating of the company’s valuation framework.
Valuation Dislocation and the Path to Re-rating
The market’s valuation discount stems from the complexity of Sihuan’s diversified structure. Traditional pharmaceutical valuation frameworks do not fully capture the company’s hybrid model, and thus we believe a “conglomerate discount” has been applied. However, key shifts are creating a window for this discount to unwind:
Change 1: Re-rating of the medical aesthetics platform value. The market still treats Sihuan’s aesthetics segment as a product-led business, overlooking its evolution into a platform with full-spectrum R&D, nationwide channel penetration, and AI-enhanced capability. This structural shift merits a platform-company premium.
Change 2: Commercialization momentum and equity value realization in innovative therapeutics. Both Xuanzhu Biopharmaceutical and Huisheng Biopharmaceutical are entering a phase of accelerated commercialization. Xuanzhu’s spin-off has only partially unlocked value; Huisheng’s intrinsic worth is not yet priced in. Further capital market actions—such as a potential Huisheng listing—could catalyze a broader revaluation.
Change 3: Cash reserves materially misaligned with market cap. With RMB3.89 billion in cash—nearly 30% of its market cap—this disconnect is unsustainable. Robust cash flow from the generics business provides additional capital for reinvestment and M&A.
相关文件

